STUs Major Customers, Schools Next
Of the three major bus segments of intracity, inter-city, and school buses, the intracity segment, led by State Transport Undertakings, has the lion’s share in terms of leading the EV charge. Of the current parc of around twelve lakh buses, intracity buses are estimated to be at around two lakh units.
In terms of EV adoption, Dr. Jain says the intracity segment has already reached the inflection point. “And that is where I see future demand in the intracity bus segment. I expect it to be mostly electric,” she says.
Going by the EV adoption trend in intracity bus segment, particularly by STUs, PMI Electro Mobility is bullish that the cumulative number of 50,000 e-buses under the PM e-Drive and PM eBus Sewa schemes can be achieved within the next two years.
“Initially, we received orders for electric buses from places that did not have buses, mainly due to the FAME incentives. They were like, we might as well do it. Now we've reached a stage where STUs who had their traditional diesel buses are now moving to electric fleets. They see it is cheaper,” says Dr. Jain.
Arguing for the case of electric buses, she explains that with a driving cycle of 180-200 kilometres a day, 365 days a year, the TCO (Total Cost of Ownership) “worked out very well” as the operator can potentially achieve a breakeven point by year three or four for a 12-year contract.
It is estimated that the per kilometre fuel cost of a diesel bus is around ₹30, compared to approximately ₹8 in an electric bus. And this could be the major contributor in savings of around ₹ 1.5 crore over a twelve year usage period, far offsetting the premium of around ₹ 40 lakh in the acquisition cost of an electric intracity bus, according to Dr. Jain.
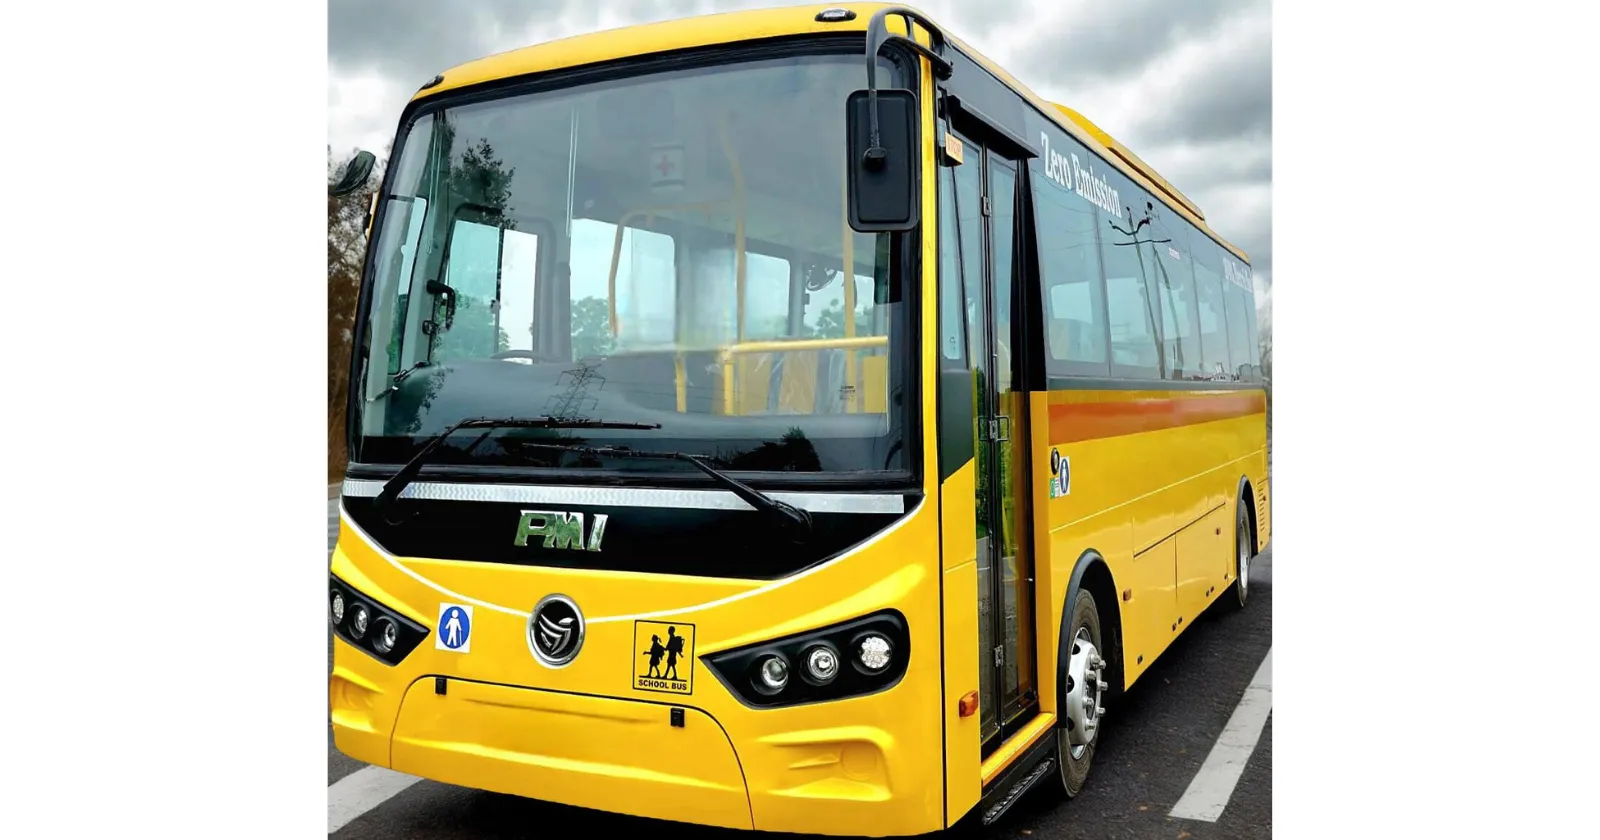
The school bus segment, with a very different set of usage dynamics, is the next segment PMI Electro Mobility wants to enter, and be one of the early movers in this space. It has bagged an order for 30 electric school buses, deliveries of which will begin next month.
School buses run around a hundred kilometres daily, for around 250 days a year. Unlike intercity buses, its replacement also happens earlier at about 8 years. These factors make it more challenging for EVs to be competitive in the school bus segment. “And that's the thing we actually worked on a lot, where we've reduced the delta between the diesel bus and school bus so much that we will make it an attractive product,” says Dr. Jain, while declining to reveal the “proprietary” approaches taken to reduce price delta.
The acquisition cost of PMI Electro Mobility’s school bus is approximately 20-30% higher than a comparable ICE version, and the “substantial” operational cost savings is being pitched as a key factor to pitch for the EV. “With fuel cost savings alone ranging between ₹25–₹30 per kilometre, customers can achieve overall opex savings of ₹60–₹70 lakhs over a 7-year period,” according to Dr. Jain. The school bus market in India is pegged at 20,000 to 30,000 units a year in India.
According to the e-bus maker, the domestic electric bus market is poised for exponential growth over the next 3–5 years, and the school bus sub-segment holds immense potential.
The introduction of competitively priced electric school buses, and the added benefits of zero tailpipe emissions, are expected to power a rapid shift toward electrification. “Furthermore, state government subsidies—often around ₹10 lakh per bus—are making the electric alternative even more attractive for fleet operators. Overall, we project electric bus sales to grow 3 to 4 times within the next three years, with the school bus segment emerging as a key driver of this momentum,” says Dr. Jain.