
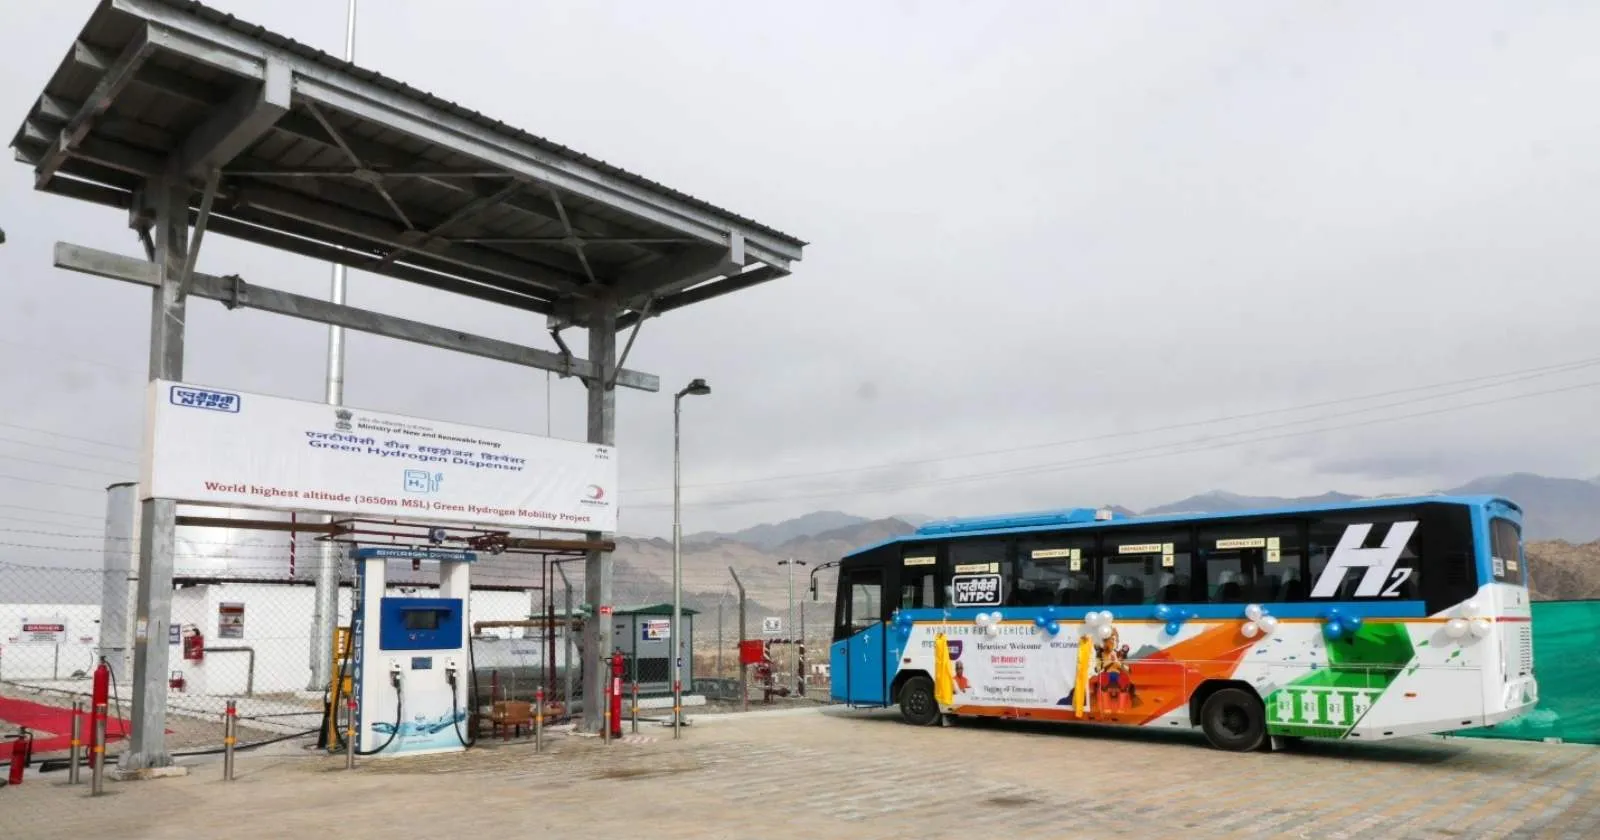
Refuelling is a challenge for hydrogen vehicles, but infrastructure is being set up across India, such as NTPC's Green Hydrogen Mobility Station in Leh, set up in November 2024.
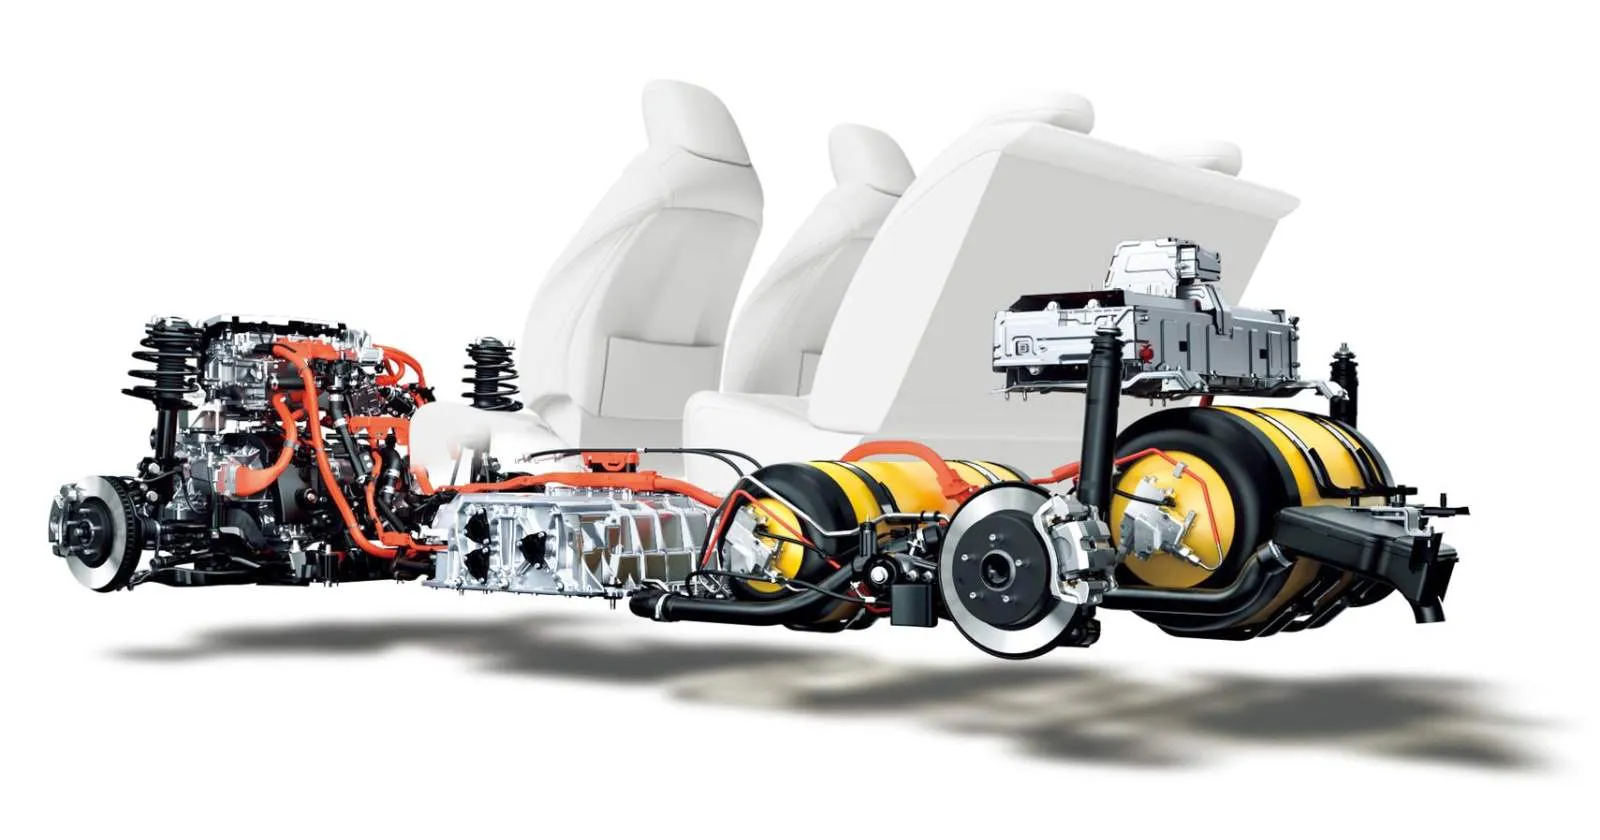
The dream of hydrogen-powered transportation traces its roots to visionary 19th-century scientists like William Grove, whose 1839 "gas voltaic battery" demonstrated the foundational principle of fuel cells, yet practical applications remained elusive for over a century. The technology gained critical momentum during the 1960s US space program, where NASA’s Gemini and Apollo missions utilised hydrogen fuel cells not merely for power but as life-support systems — producing drinking water for astronauts while validating the technology’s reliability in extreme environments. This space-era breakthrough ignited global interest, accelerated further by the 1970s oil crises that forced nations to seek alternatives to petroleum. Japan emerged as an early pioneer, with the Musashi Institute’s 1970s fuel cell prototypes, while Germany’s Daimler-Benz and BMW experimented with hydrogen internal combustion engines (H2-ICEs). The 1990s introduced environmental imperatives to the equation, as California’s Zero-Emission Vehicle (ZEV) mandate pressured automakers to explore beyond batteries. This catalytic period saw Toyota, Honda, and General Motors initiate dedicated fuel cell vehicle (FCV) programs, culminating in watershed moments like Honda’s 2008 FCX Clarity — the first leased FCV — and Toyota’s 2014 Mirai, which delivered a 500 km range and five-minute refuelling, proving hydrogen’s viability for mainstream use.
Parallel infrastructure efforts unfolded haltingly, with Japan’s JHFC initiative and Germany’s H2Mobility consortium deploying early refuelling stations, while California’s Hydrogen Highway Network aimed for 100 stations by 2020. Yet progress was uneven, hampered by costs exceeding $3 million per station and regulatory fragmentation. The 2020s witnessed a strategic pivot as hydrogen’s limitations for passenger vehicles became apparent against rapidly advancing battery electric vehicles (BEVs). Lithium-ion batteries achieved cost reductions of 89 percent between 2010–2022, capturing light-duty markets and forcing hydrogen to recalibrate toward heavy transport. Here, hydrogen’s advantages — energy density, rapid refuelling, and minimal payload penalty — proved decisive. Hyundai’s XCIENT trucks (deployed 2023 in Germany and California), Alstom’s Coradia iLint hydrogen trains (operational in Austria), and Toyota-powered fuel cell buses across Asian megacities demonstrated hydrogen’s niche: decarbonising sectors where batteries faltered. Technological strides in proton-exchange membrane (PEM) fuel cells reduced platinum loading by 80 percent since 2005, while Type IV carbon-fiber tanks enabled 700-bar storage. Yet persistent challenges included green hydrogen production costs (4–5x grey hydrogen in 2023) and global station counts barely surpassing 1,000 by 2024 — concentrated in just three regions: East Asia, California, and Western Europe. This divergence between passenger and commercial applications defined hydrogen mobility’s modern era, setting the stage for geographically fragmented adoption.
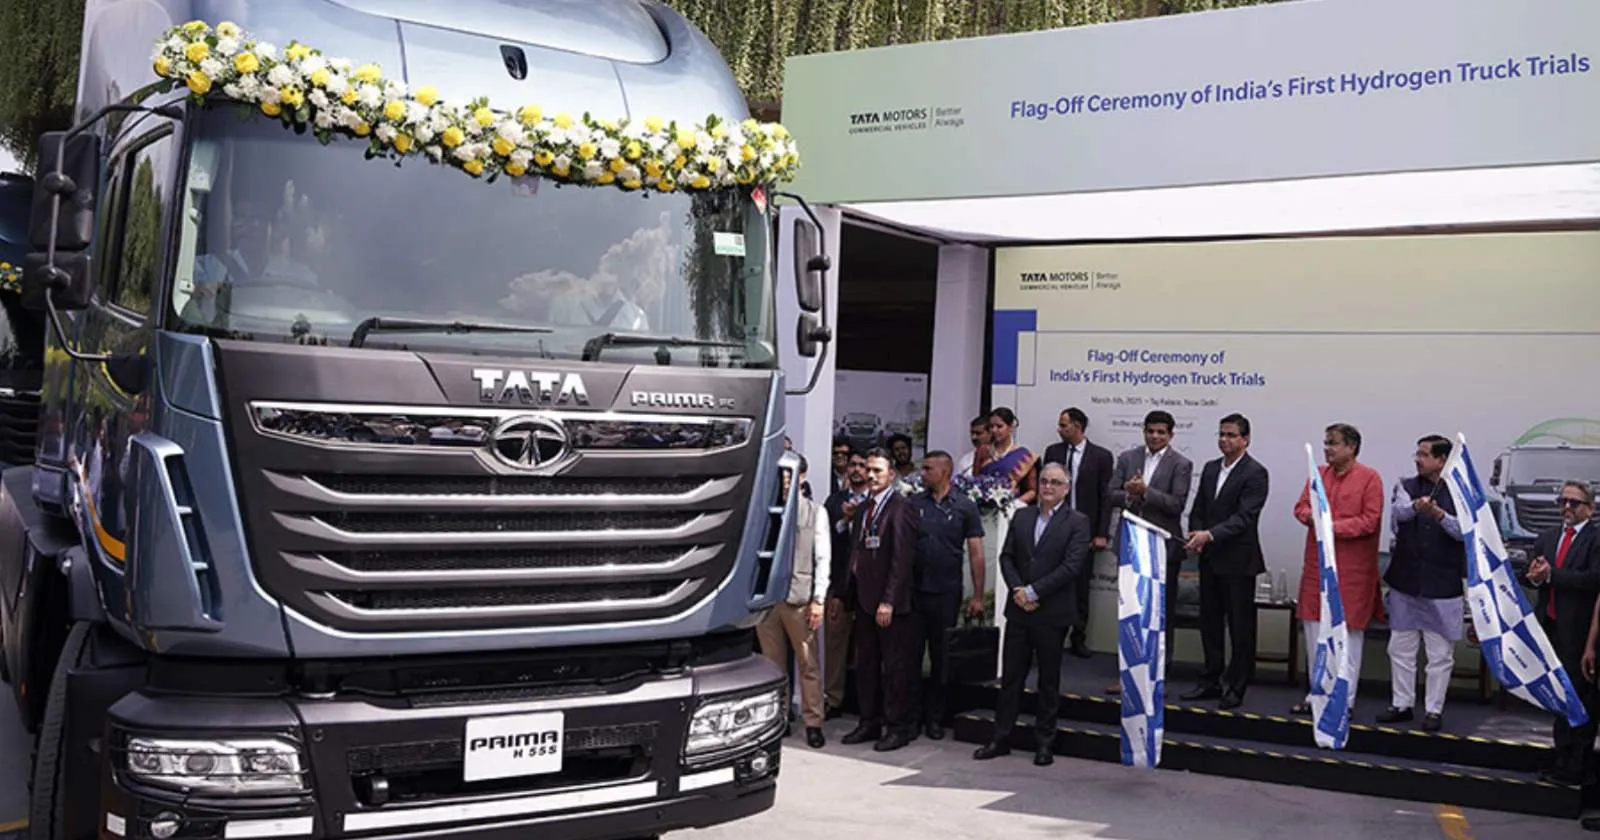
The narrative remains one of conditional success, shaped by four intersecting drivers: energy security crises (e.g., Europe’s post-Ukraine urgency), industrial policy (US IRA tax credits, China’s FCV subsidies), technological spillovers from materials science, and climate imperatives. Hydrogen’s passenger car ambitions retrenched (GM and Honda dissolved their FCV partnership in 2020), while heavy transport surged: Daimler’s GenH2 truck targets 1,000 km ranges, and Chinese manufacturers deployed 5,100 hydrogen trucks by 2023. This bifurcation underscores a hard-learned lesson: hydrogen mobility thrives not as a universal solution, but where operational demands — daily mileage exceeding 500 km, payload sensitivity, or refuelling downtime constraints — make batteries impractical.